State Retirement Plan Mandate
What States Have Them, Which States Are Pending and When Do They Take Effect?
In recent years, states across the country have enacted retirement savings programs to help individuals save for retirement. The rules of these state mandated programs vary greatly from state to state, but they could help bridge the retirement gap for as many as 41 million U.S. workers who currently don’t have access to an employer-sponsored plan. While this is an important step in fully addressing the retirement gap and its effects on the private sector, what does it mean for business owners?
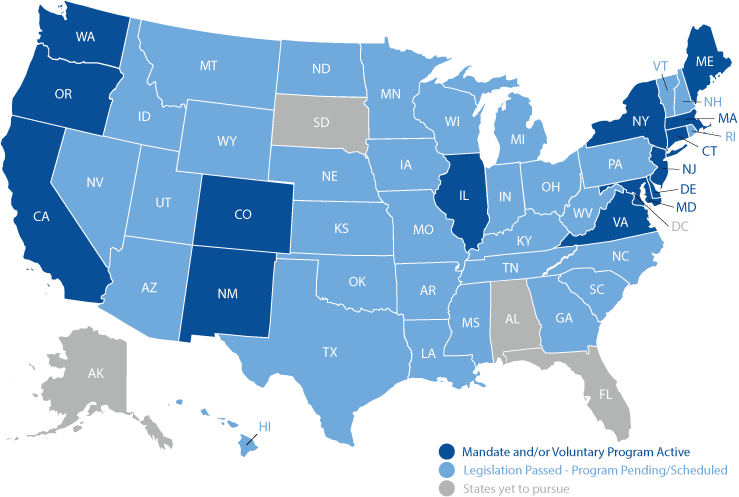
Depending on where the business operates, there are specific retirement plan adoption deadlines that companies will be required to meet to continue operating legally and avoid penalties.
At TRA we want to help close the retirement access gap, we’re incredibly excited by these new developments and the renewed interest in retirement savings. To help you decipher these mandates, we’ve broken them down by state.
Which states have mandatory retirement plans?
-
When states require employers to provide their employees with retirement savings opportunities, it’s known as a state mandated retirement. Businesses generally have two ways to comply with these laws – enroll their employees into a state-sponsored retirement program or sponsor a plan of their own through the private market, such as those offered by TRA.
-
▾
California
CalSavers
- Program: Eligible employers with one to four employees – December 31, 2025 compliance deadline
- Status: Active
- Penalties: Eligible employers that fail to comply may face a penalty of $250 per eligible employee if they remain noncompliant 90 days after receiving a notice of noncompliance. If noncompliance continues for an additional 90 days, the penalty increases by an additional $500 per eligible employee, for a total of $750 per eligible employee.
- Click here for more details to help business owners benefit.
-
▾
Colorado
Colorado Secure Savings Programs
- Program: The Colorado SecureSavings Program requires eligible employers that do not offer a qualified retirement plan to register for the program or certify an exemption. Registration is currently open. Employers generally must have five or more employees and have been in business for at least two years.
- Status: Active
- Deadline: Registration deadlines have passed. Employers that have not yet registered or certified an exemption should do so as soon as possible.
- Requirements: Generally applies to employers with five or more employees that have been in business for at least two years and do not offer a qualified retirement plan.
- Penalties: Eligible employers that fail to comply may be subject to penalties under Colorado law, including fines of up to $100 per eligible employee per year, capped at $5,000 annually.
- Click here for more details to help business owners benefit.
-
▾
Connecticut
MyCTSavings
- Program: Employers with 5 or more employees that do not offer a qualified retirement plan may be required to register for MyCTSavings or certify an exemption. MyCTSavings is Connecticut’s state-sponsored retirement savings program that provides access to retirement savings through payroll deduction Roth IRAs.
- Status: Active – Eligible employers must register for MyCTSavings or certify an exemption.
- Penalties:
- Small employers (5–24 employees): Up to $500
- Medium employers (25–99 employees): Up to $1,000
- Large employers (100+ employees): Up to $1,500
- Penalties are officially in effect following the 2025 law changes.
- Click here for more details to help business owners benefit.
-
▾
Delaware
Delaware EARNS
- Delaware EARNS is a state-sponsored retirement savings program that launched and became effective July 1, 2024. The program applies to private-sector employers that:
- Have five or more W-2 employees in Delaware,
- Have been in business for at least six months, and
- Do not offer a qualified employer-sponsored retirement plan, such as a 401(k), 403(b), SEP IRA, or SIMPLE IRA
- Status
- Passed and implemented. The program was signed into law in August 2022 and is now fully operational statewide.
- Key deadline
- Registration deadlines for previously eligible employers have passed. Employers that were required to participate should already be registered with Delaware EARNS or have certified an exemption
- Employers may certify an exemption if they offer a qualified retirement plan, have fewer than five employees, or have been in business less than six months
- Penalties
- Penalty enforcement has begun in 2026.
- Eligible employers that fail to comply may be assessed a penalty of $250 per eligible employee per year, capped at $5,000 annually.
- Click here for more details to help business owners benefit.
- Delaware EARNS is a state-sponsored retirement savings program that launched and became effective July 1, 2024. The program applies to private-sector employers that:
-
▾
Hawaii
Hawaii Retirement Savings Program
- Program: The Hawaii Saves Retirement Program (HRSP) is a state-facilitated, payroll-deduction Roth IRA program. Eligible employees will be automatically enrolled unless they choose to opt out. Contributions are deducted through payroll and deposited into a Roth IRA. Employees may adjust their contribution rate or opt out at any time.
Employers must:
-
- Be a private-sector employer in Hawaii, unless exempt because they already offer a qualifying retirement plan
- Facilitate payroll deductions and remit employee contributions to the program
- Provide required employee notices and enrollment information
Employees must be:
-
- Be eligible under program requirements once the program launches
- Be automatically enrolled unless they opt out
- Status: Not yet operational. The Hawaii Retirement Savings Program is currently under development and is projected to launch in late December 2026, provided there are no extenuating circumstances
- Upcoming deadline: No employer registration deadline has been announced. The State of Hawaii is continuing implementation activities and will provide additional guidance before program launch
- Penalties: Employers that fail to comply with program requirements may be subject to financial penalties. The State has not yet published final employer implementation deadlines on the program website.
-
▾
Illinois
My Illinois Savings Program
- Program: Employers with 5+ employees, who have been in operation for at least two years, were required to provide access to the My Illinois Savings state retirement program or a qualified retirement plan by November 1, 2023. Exempt employers include those with fewer than 5 employees, have been in business for less than two years, or who already offer an employer-sponsored retirement plan.
- Status: Active
- Upcoming deadline: All deadlines have passed.
- Penalties: Businesses with 25+ employees may face $250 per eligible employee for the first calendar year. An additional $500 per employee for each subsequent calendar of non-compliance.
- Click here for more details to help business owners benefit.
-
▾
Louisiana
- Program: Senate Bill 283 (2014) proposed the Louisiana Retirement Savings Plan, which would have established a portable retirement savings program for private-sector employees whose employers did not offer a workplace retirement plan. The bill was referred to the Senate Committee on Retirement but did not advance further and was never enacted.
- Status: Pending Legislation (No active/current state-facilitated retirement program)
- Upcoming deadline: TBD – No program has been established and there are currently no employer compliance deadlines.
-
▾
Maine
Maine Retirement Investment Trust Program (MERIT)
- Program: The Maine Retirement Investment Trust (MERIT) is a state-facilitated retirement savings program established to help employees save for retirement through payroll deductions into a Roth IRA. Eligible employers that have been in business for at least two years, have five or more employees, and do not offer a qualified retirement plan are generally required to register or certify an exemption. Employees are automatically enrolled and may opt out of participation. Employers with fewer than five employees are not required to participate but may be eligible to do so voluntarily.
- Status: Active
- Upcoming deadline: June 30, 2026 (for newly eligible employers meeting program requirements during 2025).
- Penalties: Employers that meet program eligibility requirements and fail to register or certify an exemption may be subject to state enforcement actions and penalties under Maine law.
- Click here for more details to help business owners benefit.
-
▾
Maryland
Maryland $aves
- Program: MarylandSaves is Maryland’s state-sponsored retirement savings program that provides eligible workers with access to a Roth IRA through payroll deductions. Certain Maryland employers that do not offer a qualified retirement plan are required to facilitate the program. Employers that participate in MarylandSaves or offer a qualified retirement plan may qualify for a waiver of the State’s $300 annual report filing fee.
- Status: Active
- Upcoming deadline: Eligible employers must register, begin submitting payroll contributions, or claim an exemption/waiver by the deadline provided by MarylandSaves. Employers who qualify for the annual filing fee waiver must complete the required action by December 31 of the applicable year.
- Incentive: Employers that participate in MarylandSaves or offer a qualified retirement plan may receive a $300 waiver of Maryland’s annual SDAT business filing fee.
- Penalties: At this time, there are no penalties if an employer does not offer MarylandSaves or another retirement plan. MarylandSaves materials currently emphasize employer registration requirements and available incentives.
- Click here for more details to help business owners benefit.
-
▾
Massachusetts
CORE Plan
- Program: The Massachusetts Defined Contribution CORE Plan is a state-sponsored 401(k) multiple employer plan (MEP) available to eligible Massachusetts nonprofit organizations. Nonprofits with 100 employees or fewer may be eligible to adopt the CORE Plan. The Commonwealth assumes many administrative and investment responsibilities, helping reduce the burden on participating nonprofit employers. Participants must have payroll administered through an eligible payroll provider.
- Status: Active
-
▾
Minnesota
Minnesota Establishes State-Sponsored ‘Secure Choice’
- Program: All Minnesota employers with five or more employees that do not currently sponsor a retirement plan will be required to participate. Eligible employees will contribute a portion of their pay into IRAs (individual retirement accounts). The default retirement account will be a Roth IRA (i.e., contributions will be made after taxes), unless the covered employee elects to contribute on a pretax basis.
- Status: Actively rolling out.
- Upcoming deadlines:
Number of employees at covered employer Implementation Timeline 100 or more June 30, 2026 50 to 99 Dec. 31, 2026 25 to 49 June 30, 2027 10 to 24 Dec. 31, 2027 5 to 9 June 30, 2028 - Penalties for Non-Compliance:
- Months 1-6: Enrollment-window reminders
- Months 7-18: Written noncompliance notices
- Months 19-24: Contact plus 2 certified letters
- After month 24: $100 per employee, maximum $4,000
- Months 25-36: $200 per employee, maximum $6,000
- Months 37-48: $300 per employee, no maximum
- Each ongoing year: $500 per employee, no maximum
- Click here for more details to help business owners benefit.
-
▾
Missouri
Show-Me MyRetirement Savings Plan
- Program: The Show-Me MyRetirement Savings Plan is a voluntary multiple-employer retirement plan available to eligible employers, self-employed individuals, and certain associations. The program allows for voluntary pre-tax and Roth 401(k) contributions and is intended to expand retirement plan access for small employers. Eligible employees may be automatically enrolled, with the ability to opt out.
- Status: Active
- Penalties: None. Participation in the Show-Me MyRetirement Savings Plan is voluntary, and the enabling statute does not establish employer noncompliance penalties.
-
▾
Nevada
Nevada Employee Savings Trust (NEST)
- Program: The Nevada Employee Savings Trust (NEST) is a state-facilitated retirement savings program administered by the Nevada Treasury. NEST provides eligible workers with access to a Roth IRA through payroll deductions. Eligible employers that do not offer a qualified retirement plan are required to facilitate the program, while employee participation remains voluntary. Employees are automatically enrolled and may opt out at any time.
- Status: Active. NEST is operational and accepting employer registrations and employee participation.
- Employers affected: Participation is mandatory for eligible employers that do not offer a qualified retirement plan. Employees are automatically enrolled unless they elect to opt out.
- Penalties: Employers who fail to comply may be subject to penalties.
- Click here for more details to help business owners benefit.
-
▾
New Jersey
RetireReady NJ
- Program: Both for-profit and nonprofit employers that have been in business for at least two years and do not offer a qualified retirement plan may be required to participate in RetireReady NJ. The program is currently accepting registrations from employers with 10–24 employees, and employers with 25 or more employees were previously required to register. Eligible employees are automatically enrolled and may opt out.
- Status: Active
- Deadline: Registration deadlines have passed for employers with 25 or more employees. Registration is currently open for employers with 10–24 employees.
- Penalties:
- Year 1: Written warning
- Year 2: $100 per employee
- Years 3–4: $250 per employee
- Year 5 and beyond: $500 per employee
- Click here for more details to help business owners benefit.
-
▾
New Mexico
NM Work and Save IRA, NM Retirement Plan Marketplace
- Program: On February 26, 2021, Gov. Michelle Lujan Grisham signed the New Mexico Work and Save Act, creating a voluntary Roth IRA savings option for private-sector employees, nonprofit employees, and self-employed individuals without employer-sponsored retirement plans, along with the New Mexico Retirement Savings Plan Marketplace, a web-based marketplace of private-sector retirement plan providers.
- Status: The New Mexico Work and Save Board continues to oversee development of the Work and Save IRA program and Retirement Savings Plan Marketplace. The program has not yet launched and participation is not currently required.
- Deadline: Registration deadlines have not been established. Participation remains voluntary for both employers and employees.
- Penalties: No penalties exist at this time.
- Since participation is voluntary, there are currently no employer penalties or enforcement provisions for non-participation.
-
▾
New York
New York Secure Choice
- Program: The New York Secure Choice Savings Program is a state-facilitated retirement savings program for private-sector employees who do not have access to a retirement plan at work. Eligible employers that do not offer a qualified retirement plan are required to facilitate the program. Through automatic enrollment and payroll deduction, employees contribute to Roth Individual Retirement Accounts (IRAs).
- Status: Active. Registration is open for eligible employers.
- Penalties: Proposed, but not yet final/enforced.
- Click here for more details to help business owners benefit.
-
▾
Oregon
OregonSaves
- Program: Oregon employers that do not offer a workplace retirement plan must register for OregonSaves or certify an exemption. OregonSaves provides workers with access to an Individual Retirement Account (IRA) through payroll deductions.
- Status: Active
- Upcoming deadline: Employers must complete registration or certify an exemption by their required deadline. New businesses may have different registration timelines based on when they begin operations.
- If you start a business in Oregon:
- January 1 – March 31: Register by July 31 of the same year
- After March 31: Register by July 31 of the following year
- If you start a business in Oregon:
- Penalties: Up to $100 per eligible employee, not to exceed $5,000 per year.
- Click here for more details to help business owners benefit.
-
▾
Vermont
VTSaves
- Program: The VT Saves program establishes a retirement savings program for Vermonters who are not currently offered a retirement plan through their employer. The program is designed to make saving for retirement easy and automatic through payroll deductions into a Roth IRA, at no cost to employers and no ongoing cost to taxpayers.
- Status: Active. VT Saves is operational and eligible employers are required to register or certify an exemption.
- Upcoming deadline: Registration deadlines for covered employers were phased in as follows:
- July 1, 2025 (25+ employees), January 1, 2026 (15-24 employees),
- July 1, 2026 (5-14 employees)
- Penalties:
- Prior to October 1, 2025: Maximum penalty is $10 per covered employee.
- October 1, 2025 to September 30, 2026: Maximum penalty is $20 per covered employee.
- On and after October 1, 2026: Maximum penalty is $75 per covered employee.
-
▾
Virginia
RetirePath Virginia
- Program: RetirePath Virginia is a state-facilitated retirement savings program created by Virginia law to expand access to retirement savings. Eligible employers must register for RetirePath Virginia or certify an exemption if they offer a qualified retirement plan. Participation is voluntary for employees.
- Status: Active. Registration is open for eligible employers.
- Penalties: Employers that fail to comply may be subject to penalties of up to $200 per eligible employee per year, subject to applicable waiver provisions under Virginia law.
- Deadline: Registration is currently open for eligible employers. Employers receive a notification and Access Code when it is time to register or certify an exemption.
- Click here for more details to help business owners benefit.
-
▾
Washington
Washington Saves
- Program: Washington Saves is a state-administered auto-IRA retirement savings program established by Washington law to expand access to retirement savings for workers whose employers do not offer a retirement plan.
- Upcoming deadline: Washington Saves is scheduled to launch in 2027.
- Status: Coming 2027. Washington Saves will provide retirement savings access for workers whose employers do not offer a workplace retirement plan.
- Penalties: To be confirmed and established.
- Click here for more details to help business owners benefit.
-
TRA State Retirement Plan Mandates Frequently Asked Questions (FAQ's)
-
-
▾
What is a state retirement plan mandate?
A state retirement plan mandate is a law requiring certain employers to provide workers with access to a retirement savings option. In most cases, an employer can comply by registering for the state-sponsored program or by offering a qualified employer-sponsored retirement plan.
-
▾
Do employers have to use the state-sponsored retirement program?
No. In many states, employers can meet the requirement by offering their own qualified retirement plan instead of using the state program. This is often the key decision point for employers comparing compliance, plan design flexibility, and long-term benefits.
-
▾
Which employers are affected by state retirement mandates?
Eligibility rules vary by state, but they typically depend on factors such as employee count, time in business, and whether the employer already offers a qualified retirement plan. Because the rules differ by state, employers should review the requirements for every state in which they operate.
-
▾
What happens if an employer misses a state retirement plan deadline?
Missing a deadline can lead to fines, notices, or other penalties, depending on the state. Employers should confirm their deadline as early as possible and determine whether they need to register for the state program or implement a private plan.
-
▾
Is a 401(k) better than a state-mandated retirement program?
For many employers, a 401(k) offers more flexibility than a state-mandated program, including plan design options, employer contribution strategies, and a stronger benefits package for recruiting and retention. The right choice depends on business goals, workforce needs, and administrative preferences.
-
▾
How can financial advisors help clients with state retirement plan mandates?
Financial advisors can help clients determine whether they are subject to a mandate, compare the state program to private plan options, and build a retirement strategy that supports compliance and employee outcomes. This can turn a compliance requirement into a broader planning opportunity.
-
▾
Can a business avoid state mandate penalties by starting a retirement plan?
In many cases, yes. If the employer adopts a qualified retirement plan that satisfies the state’s exemption rules, that may allow the business to comply without enrolling in the state-sponsored program. Employers should confirm the timing and exemption requirements in the applicable state.
-
Alternative TRA Solutions to Consider
For businesses who want to sponsor a retirement plan, some plans to consider include:
• 401(k)
• Safe Harbor 401(k)
• Cross Tested Profit-Sharing Allocation
• 401(k) plus Cash Balance Plan
Other alternatives to state retirement plan mandates include SIMPLE 401(k) Plans, Group 401(k) Plans (MEPs, PEPs and Aggregation Programs), and 403(b) Plans (for non-profits).
Working closely with you, TRA will create a customized plan that meets your client’s business. We partner with top recordkeepers and investment managers around the country and deliver exceptional client service. We also offer 3(16) Fiduciary Services to relieve business owners of day-to-day plan administration responsibilities and manage their fiduciary risk.
Complete the form below and a Regional Plan Consultant will be in contact with you.